Grow a More Profitable Business With Bookkeeping and Tax Strategy Built for Small Business Owners
Profit Pilot helps entrepreneurs take control of their books, reduce taxes, increase cash flow, and build a healthier business today—so you can eventually exit on your own terms.
Why Work With Profit Pilot?
Because most bookkeepers just enter transactions.
We help you build a more profitable business.
We give small business owners something they rarely get:
clear books, real tax planning, and a strategy for increasing profit year after year.
Here’s the difference:
We don’t hand you reports and wish you luck
We do help you find tax savings you’re currently missing
We do show you how to increase cash flow quickly
We do help you understand your numbers so you can make better decisions
We use modern, automated systems, not spreadsheets and guesswork
We bring a business-owner mindset, not an accountant mindset
We help you plan for your eventual exit, even if it's years away
You’re not looking for someone to “do your books.”
You’re looking for someone who helps you make more money.
That’s what we do.
We Specialize in Service-Based Small Businesses
Profit Pilot supports the types of businesses that need clean books and strong tax strategy, not corporate-level complexity.
Our ideal clients include:
Contractors & construction trades
Home service providers
Solo entrepreneurs
Marketing agencies & freelancers
Health, wellness, and beauty professionals
Local service businesses
Consultants and coaches
We proudly serve Austin, Leander, Cedar Park, Round Rock, and Georgetown, with clients expanding statewide.
If your business runs on hustle, service, and reputation—we’re the financial partner you’ve been missing.
Our Services
We don’t just keep your books clean—we help you use your numbers to build a stronger, more profitable business.
Profit Pilot gives you the financial clarity, tax strategy, and advisory support you need to grow with confidence.
Monthly Bookkeeping
Accurate, organized, tax-ready books every month—powered by modern tools and simple workflows. You always know exactly where your business stands.
Catch-Up & Cleanup Bookkeeping
Behind on months (or years) of bookkeeping? We’ll get everything caught up, corrected, compliant, and ready for tax planning.
Profit First Consulting
Stop wondering where your money goes. Start taking home profit intentionally. We build and support your Profit First system so it actually works.
Business & Personal Tax Preparation
Tax prep designed for small business owners—not cookie-cutter filings. We make sure your books and tax strategy work together.
Strategic Tax Planning
Year-round tax planning for your business or personal taxes. Whether we are helping you to create a tax free retirement or improve your business' tax situation, we think ahead so you’re never surprised..
Cash Flow Strategy & 7 Levers Profit Acceleration
Grow profit without working harder. We help you identify the small levers that create big financial wins in your business. With our Proprietary Seven Levers Profit Strategy (tm) we help you build the business you always wished you had.
About Profit Pilot Tax & Financial Services
Profit Pilot was created with a simple mission:
Most business owners don’t start companies because they love bookkeeping and taxes.
(If they did, the world would look very different.)
They start because they’re talented, passionate, and great at serving their customers.
But eventually the numbers catch up… and that’s where things usually fall apart.
After decades of running businesses and working with entrepreneurs, I realized something:
Small business owners don’t need another accountant—they need a financial partner.
Profit Pilot exists to give business owners clarity, confidence, and direction.
No guesswork. No jargon. No surprises at tax time.
My Background (Jeff here)
I’ve spent over 30 years as a business owner, wealth advisor, retirement planner, and profit strategist. I’ve worked with hundreds of entrepreneurs across industries—from solo consultants to contractors to local service companies.
Along the way, I saw the same pattern: when you clean up the books, plan taxes proactively, and focus on profitability… everything changes.
So Profit Pilot was born from a simple idea:
Give small business owners the tools and support they need to build profitable, sustainable businesses—and eventually walk away on their own terms.
When you work with us, you’re not just hiring a bookkeeper.
You’re getting a partner who’s in the trenches with you.
Our Mission
Lorem ipsum dolor sit amet, consectetuer adipiscing elit. Aenean commodo ligula eget dolor.
Our Philosophy
We believe small business owners deserve more than compliance—they deserve clarity, confidence, and a financial partner who helps them grow. Profit isn’t an accident; it’s the result of clean books, smart tax planning, and intentional strategy. Our philosophy is simple: when you understand your numbers, you can change your future.
Our Promise
We promise to treat your business like it matters—because it does. We communicate clearly, keep your books accurate, plan your taxes proactively, and always focus on increasing your profitability. No jargon. No judgment. Just real support that helps you make better decisions every day.
Our Guarantee
We guarantee you’ll always know where your business stands financially. You’ll get clean books, transparent reporting, and guidance you can trust. And if something doesn’t make sense, we’ll explain it until it does. Your success is the only measure that matters.
Our Blogs
S-Corp vs. LLC: Which One Saves a Profitable Business More in Taxes?
S-Corp vs. LLC: Which One Saves a Profitable Business More in Taxes?
An LLC is a legal structure and an S corporation is a tax election, so the real comparison is between an LLC taxed the default way and an LLC (or corporation) that has elected S corporation status.
The S election lets you split your profit into a reasonable W-2 salary and a distribution, and only the salary gets hit with payroll tax. That saves real money once profits are consistently in the low six figures, but the savings are smaller than most people claim because the S election also shrinks your 20% qualified business income deduction.
What is the actual difference between an LLC and an S corp?
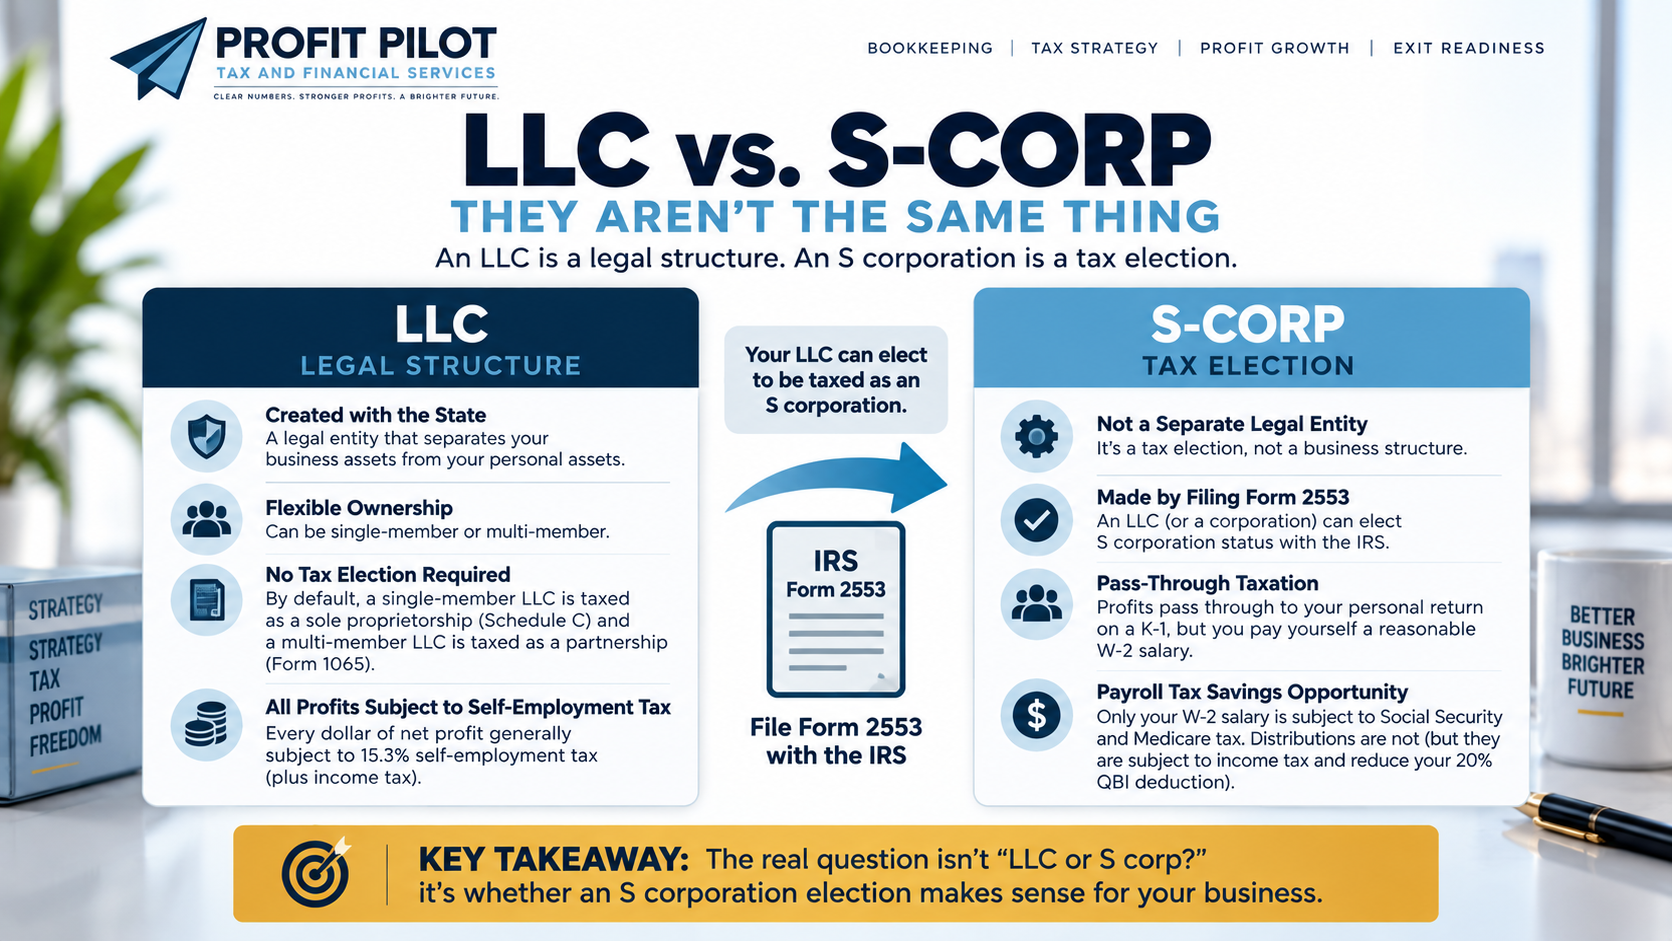
This is the part that trips up almost every owner I talk to, so let me clear it up before we go anywhere else. An LLC, or limited liability company, is a legal entity you form with the state. It exists to separate your business assets from your personal assets. It says nothing at all about how you are taxed.
An S corporation is not an entity. It is a tax election, made by filing Form 2553 with the IRS, that changes how an existing entity reports its income. An LLC can make that election. So can a regular corporation. When people say "should I be an LLC or an S corp," what they are really asking is "should my LLC keep its default tax treatment, or should it elect to be taxed as an S corporation?"
By default, a single-member LLC is taxed as a sole proprietorship on Schedule C, and a multi-member LLC is taxed as a partnership on Form 1065. In both cases, every dollar of net profit flows to your personal return, and every dollar of it is generally subject to self-employment tax. Self-employment tax is the Social Security and Medicare tax that a W-2 employee splits with their employer. When you work for yourself, you pay both halves.
Here is what that costs in 2026. The Social Security piece is 12.4% on the first $184,500 of net self-employment earnings. The Medicare piece is 2.9% with no cap at all, plus an additional 0.9% on earnings above $250,000 for joint filers or $200,000 for single filers. Combined, that is 15.3% on the bulk of your profit, sitting on top of whatever ordinary income tax you owe.
How does the S corporation election actually save money?
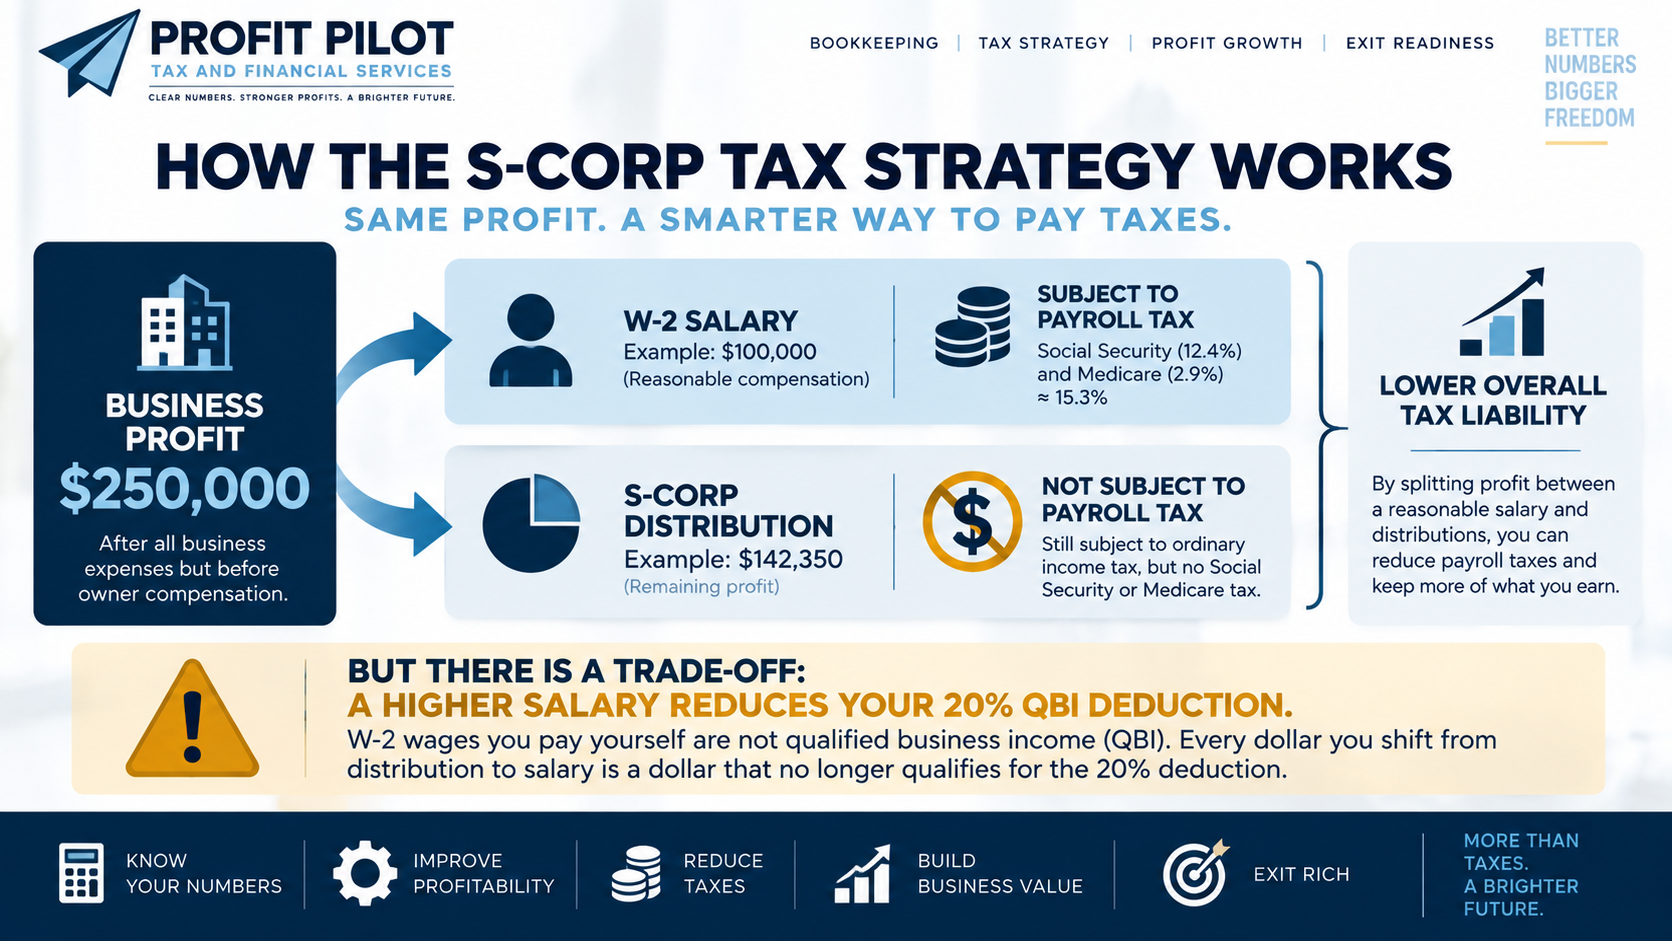
When your LLC elects S corporation status, you stop being a self-employed owner in the eyes of the payroll tax rules and become an employee of your own company. You put yourself on payroll, pay yourself a reasonable salary, and withhold and remit Social Security and Medicare tax on that salary just like any employer would. The remaining profit passes through to you on a Schedule K-1 as a distribution.
That distribution is still subject to ordinary income tax. It is not subject to Social Security or Medicare tax. That gap is the entire savings mechanism, and it is why the S election gets talked about so much.
But here is the part the seminar crowd leaves out, and as I tell my clients, it is the part that changes the answer. Section 199A, the qualified business income deduction, lets most pass-through owners deduct up to 20% of their business income. The One Big Beautiful Bill Act made that deduction permanent in 2025, so it is not going anywhere. The problem is that W-2 wages you pay yourself don't count as qualified business income. Every dollar you shift from distribution into salary is a dollar that no longer qualifies for the 20% deduction. So the S election gives with one hand and takes with the other, and you have to run both numbers to know where you actually land.
What do the numbers look like on a real business?
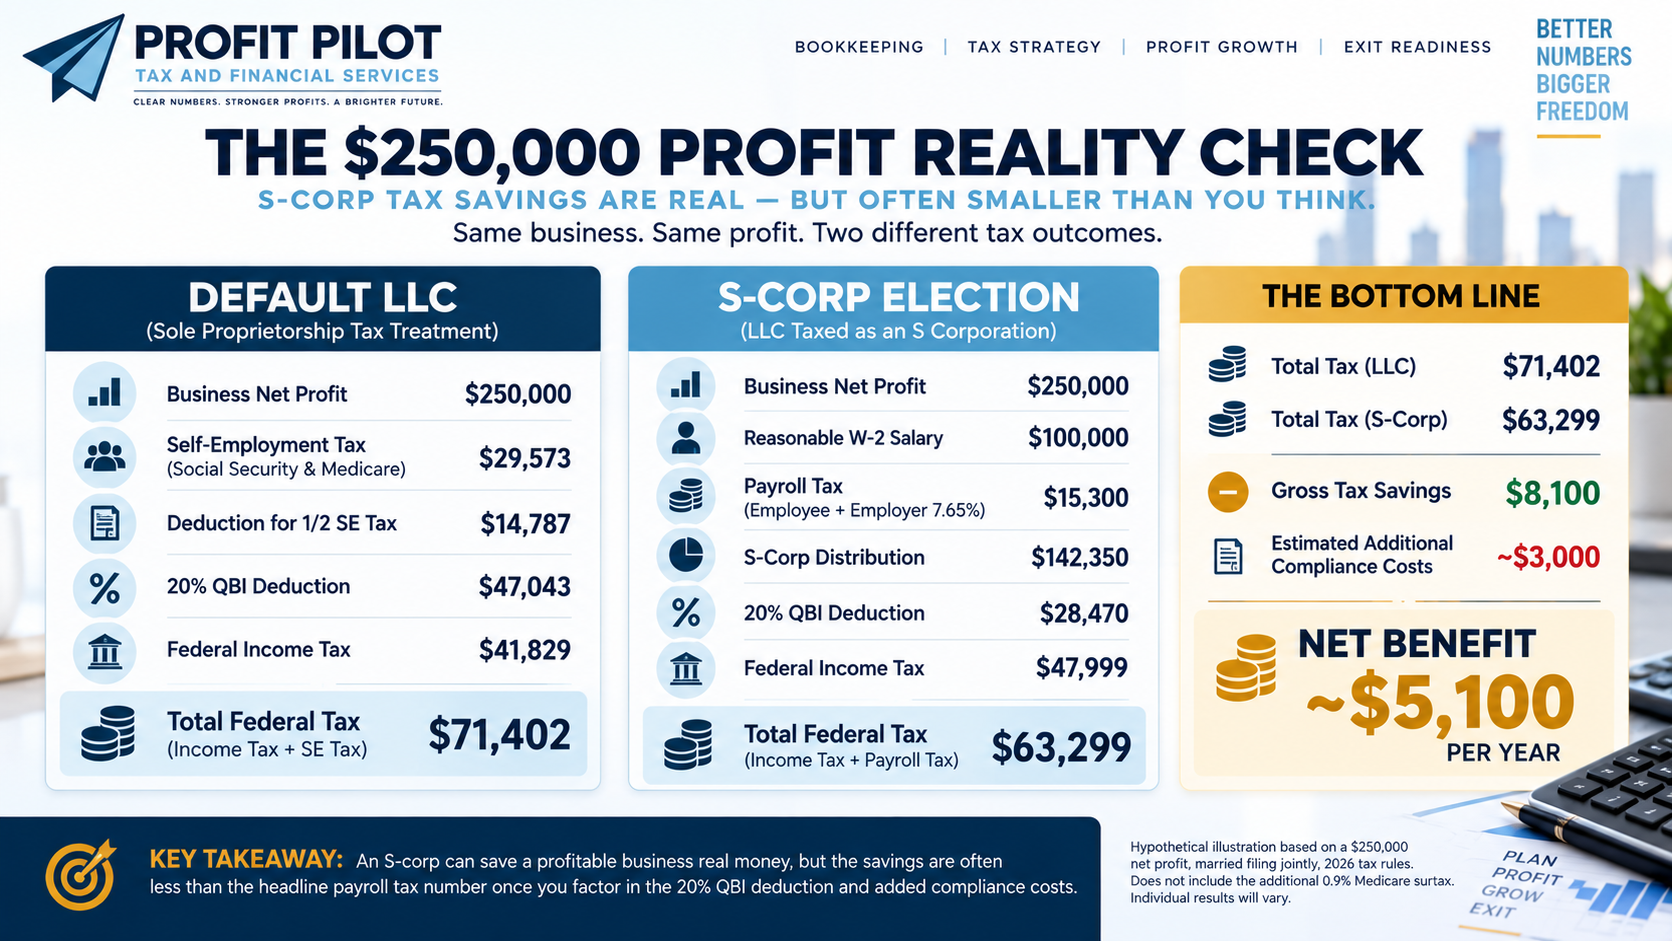
Let me put this on a specific set of facts. These figures are hypothetical illustrations, not projections, and your own result will depend on your income, your filing status, your state, and your business. To keep the comparison readable, I am setting aside the additional 0.9% Medicare surtax, which would add a few hundred dollars to the first option and nothing to the second.
Marcus runs a commercial services company in Austin as a single-member LLC. The business nets $250,000 after all expenses, but before anything he takes out. He files jointly, and his spouse has $80,000 of W-2 income from a job outside the business. They take the standard deduction, which is $32,200 for joint filers in 2026.
Option A, the default LLC. All $250,000 is self-employment income. After the standard 92.35% adjustment, his self-employment tax base is $230,875. Social Security tax runs 12.4% on the first $184,500, or $22,878. Medicare runs 2.9% on the whole $230,875, or $6,695. His self-employment tax is about $29,573, and he deducts half of it, roughly $14,787, above the line. His qualified business income is $250,000 minus that $14,787, so his 199A deduction is about $47,043. Run that through the joint brackets, and his federal income tax is roughly $41,829. Add the self-employment tax and his total federal bill is about $71,402.
Option B, the S corporation election. Marcus puts himself on payroll at a reasonable salary of $100,000. The company owes employer Social Security and Medicare of 7.65%, or $7,650, and withholds the same $7,650 from his paycheck, so $15,300 of payroll tax total. After his salary and the employer tax, $142,350 flows through on his K-1. That $142,350 is his qualified business income, so his 199A deduction drops to $28,470. His federal income tax rises to roughly $47,999. Add the $15,300 of payroll tax and his total federal bill is about $63,299.
So the S election saves Marcus roughly $8,100 a year. Notice how that number is built. He saved $14,273 in payroll tax, which is the headline number every promoter quotes. But he gave back $6,170 in additional income tax because his 199A deduction shrank by more than $18,000. The real savings is the difference, not the headline.
Then subtract the cost of running it. A payroll service, quarterly 941 filings, a separate Form 1120-S return, and the extra bookkeeping usually run somewhere between $2,000 and $3,500 a year for a business this size. Call it $3,000. Marcus nets about $5,100.
Is $5,100 a year worth doing? Yes, absolutely, and it compounds. But it is not the "save 15.3% on everything" story you hear at the lunch seminar, and an owner who elects S status at $80,000 of profit often finds the compliance cost eats the entire benefit.
What is "reasonable compensation," and why does the IRS care so much?
The whole strategy rests on one number, and that number is the salary you pay yourself. The tax code requires an S corporation shareholder who performs services to be paid reasonable compensation before taking distributions. If you pay yourself $30,000 and distribute $220,000, you have not found a loophole. You have created an exam issue, and the IRS has recharacterized distributions as wages in enough cases that the pattern is well established. In Watson v. Commissioner, an accountant paying himself $24,000 while distributing well over $175,000 had his compensation reset to $91,044, with back payroll taxes, interest, and penalties on top.
There is no bright-line percentage, no matter what you have read. The IRS looks at your training and experience, your duties and hours, what comparable businesses pay for comparable work, your dividend history, payments to non-shareholder employees, and what a similar company would have to pay to hire someone to do what you do. The practical test I use with clients is simple: if you had to replace yourself tomorrow with a hired manager, what would the market charge you? That is roughly your salary. Document how you arrived at it, keep the comparables in your file, and revisit it every year as the business changes.
When does the S election stop making sense?
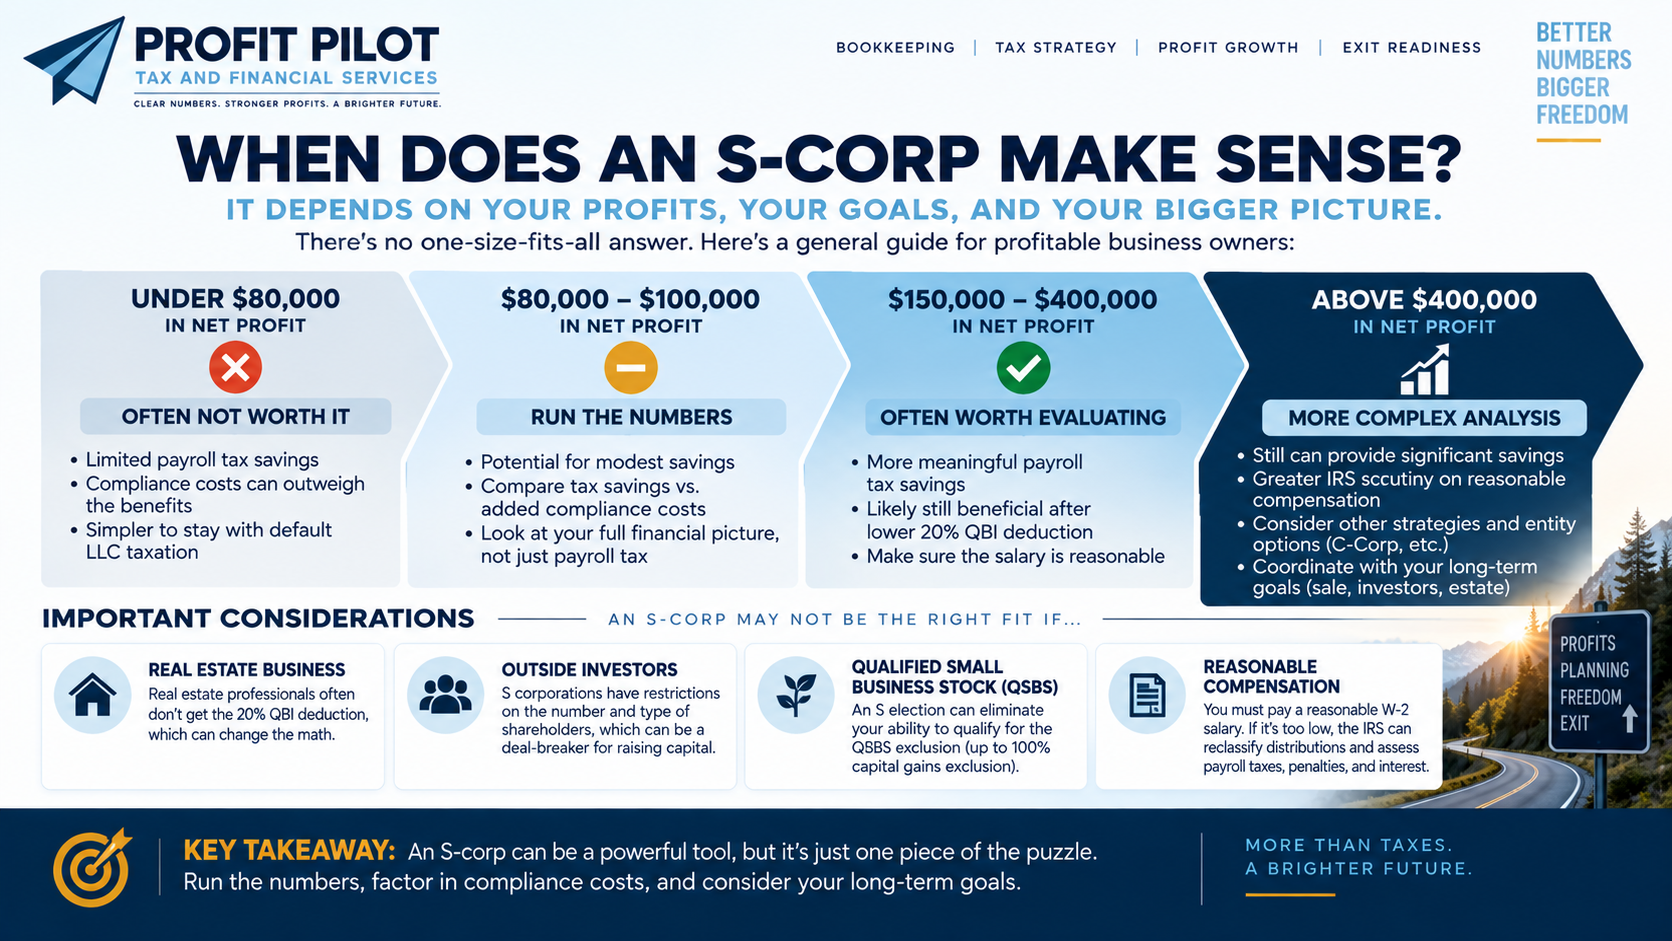
A few situations where I slow owners down.
If your profit is inconsistent or under roughly $80,000 to $100,000, administrative costs often swamp the benefit, and you lose flexibility for very little. If most of your profit is already above the Social Security wage base, the incremental savings on those dollars is only the 2.9% Medicare rate rather than 15.3%, so the benefit flattens out faster than people expect.
If your business holds appreciating real estate, be careful. Getting property out of an S corporation later is a taxable event, and there is no easy fix. Real estate generally belongs in a partnership or a separate LLC, not inside your operating S corp.
If you might ever want qualified small business stock treatment under Section 1202, which can exclude a large chunk of gain when you sell, know that QSBS requires C corporation stock. S corporation stock does not qualify. That is a genuine exit planning fork in the road, and it is worth thinking about years before a sale rather than months.
Finally, S corporations carry ownership restrictions: no more than 100 shareholders, only one class of stock, and no partnership, corporate, or nonresident alien owners. If you plan to bring in outside investors, grant profits interests, or make special allocations among partners, a partnership-taxed LLC is usually the more flexible home.
Does the answer change because you are in Texas?
Less than you might hope, and that is good news. Texas has no personal income tax, so there is no state income tax difference between the two choices, and the federal math above is essentially the whole story. Texas imposes a franchise tax on both LLCs and S corporations, with a no-tax-due threshold of $2.65 million in total revenue for the 2026 report year, and you still have to file an information report even when you owe nothing.
How does this affect what happens when you sell?
Buyers usually want an asset purchase for the step-up in basis, and sellers usually want a stock sale for capital gain treatment. An S corporation can bridge that gap through a Section 338(h)(10) or 336(e) election, which lets the buyer treat a stock purchase as an asset purchase for tax purposes. That flexibility is a genuine advantage of the S election when it comes time to sell.
On the other side, if your business owns appreciated assets or you had C corporation history in the last five years, the built-in gains rules can bite. None of this is a reason to elect or not elect today, but all of it is a reason to make the choice with your exit in view rather than just this April's tax bill.
Key takeaways
An LLC is a legal entity and an S corporation is a tax election. Most owners are really deciding whether their LLC should elect S status.
Default LLC taxation subjects essentially all profit to self-employment tax: 12.4% Social Security on the first $184,500 in 2026, plus 2.9% Medicare with no cap.
The S election splits profit into a reasonable W-2 salary (payroll taxed) and a distribution (not payroll taxed).
The 20% qualified business income deduction offsets part of the savings, because W-2 wages you pay yourself are not qualified business income.
In a $250,000 profit example, the payroll tax savings of about $14,273 netted down to roughly $8,100 after income tax, and roughly $5,100 after compliance costs.
Reasonable compensation is the entire risk point. Underpaying yourself invites recharacterization, back taxes, interest, and penalties.
S corporations are a poor home for appreciating real estate and disqualify you from QSBS, but they offer real flexibility at sale through a 338(h)(10) or 336(e) election.
Frequently asked questions
At what profit level does the S corporation election usually start to pay? There is no magic number, but for most owners the math starts working somewhere around $80,000 to $100,000 of consistent net profit, and it gets clearly worthwhile in the $150,000 to $400,000 range. Below that, payroll and tax prep costs tend to consume the savings. Above roughly $400,000 of household income, the QBI rules change shape and the analysis needs a fresh look.
Can I keep my LLC and still be taxed as an S corporation? Yes, and that is what most owners do. You keep the LLC with the state, keep your operating agreement, keep your EIN, and simply file Form 2553 to elect S corporation tax treatment. Nothing about your legal structure changes. You do have to start running actual payroll, which is the part people underestimate.
What happens if I pay myself too little salary? If the IRS examines the return and concludes your compensation was unreasonably low, it can recharacterize distributions as wages. That means back Social Security and Medicare tax, interest, and potentially accuracy or failure-to-deposit penalties. The exposure is not limited to one year, which is why documenting your salary decision each year matters more than picking a perfect number.
Does an S corporation reduce my income tax or just payroll tax? It reduces payroll tax, but in most cases it slightly increases income tax because of the smaller QBI deduction. If someone tells you it cuts your income tax, they are describing something else.
Is there a deadline to make the election? Generally, the election must be filed by the fifteenth day of the third month of the tax year you want it to take effect, so around March 15 for a calendar-year business. Relief for late elections is available in many circumstances under Revenue Procedure 2013-30, but relying on relief is a worse plan than filing on time.
Should I consider a C corporation instead? Sometimes, though it is a narrower fit than the internet suggests. A C corporation pays a flat 21% corporate rate, and then dividends are taxed again at the shareholder level, which is a real cost for an owner who needs the cash. It can make sense if you retain most of your earnings in the business, if you plan to raise institutional capital, or if you are building toward a QSBS exclusion at sale.
About Jeff Kikel
Jeff Kikel, ChFC, CRPC, ATA, is the founder of Profit Pilot Tax and Freedom Day Wealth Management in the Austin, Texas area. He works with business owners on tax strategy, value building, and planning a business exit that actually funds the life they want afterward. Jeff is the co-host of The Cents of Things podcast and writes and speaks regularly on business value, taxes, and retirement income.
If you are trying to decide whether an S corporation election fits your business, or you suspect the salary you have been paying yourself has drifted from defensible levels, Profit Pilot can run the numbers with you and put a documented reasonable compensation position in your file. Learn more at www.ProfitPilotTax.com.
This article is for educational purposes only and is not individualized tax, legal, or investment advice. Tax law is complex and changes over time, and the right answer depends entirely on your specific facts, entity structure, income, state, and timeline. The dollar figures used above are hypothetical illustrations, not projections, and no particular outcome is promised or guaranteed. Please consult your own tax advisor, attorney, or financial professional before acting on anything you read here.
Sources
IRS: S Corporation Compensation and Medical Insurance Issues
IRS: Instructions for Form 2553, Election by a Small Business Corporation
IRS: Self-Employment Tax (Social Security and Medicare Taxes)
Social Security Administration: 2026 Contribution and Benefit Base
Tax Foundation: 2026 Tax Brackets and Federal Income Tax Rates
Warren Averett: OBBBA Breakdown, Qualified Business Income Deduction
Foster Garvey: One Big Beautiful Bill Act, Part IV, Code Section 199A
Frequently Asked Questions
Q:
What types of businesses do you work with?
We specialize in solo entrepreneurs, contractors, trades, and service-based businesses. If you run a small business and want clean books, lower taxes, and higher profit, you’ll fit right in here.
Q:
Do I have to be located in Austin to work with you?
.No. While we proudly serve Austin, Cedar Park, Leander, Round Rock, and Georgetown, we work with businesses across Texas and nationwide. Everything we do is digital, secure, and easy to use.
Q:
What makes Profit Pilot different from other bookkeeping or tax firms?
Most firms focus only on compliance—we focus on profitability. You get modern bookkeeping, proactive tax planning, and real advisory support using the Profit First system and the 7 Levers Profit Framework.
Q:
Do you offer tax planning or just tax preparation?
We do both. Tax prep handles what happened last year. Tax planning helps you reduce what you owe going forward. We work year-round to help you keep more of what you earn.
Get in touch with us
Get in Touch With Us
Not sure where to start? That’s okay.
A quick conversation can bring a lot of clarity.
Book a consultation, and we’ll help you understand your numbers, explore your options, and decide what makes the most sense for your business—no obligation.
737-808-2704
1320 Arrow Point Dr Ste 501 Office 2, Cedar Park, TX 78613
Monday - Friday, 9:00 am - 4:00 pm
Send us a message
Follow Us
Follow Us
Profit Pilot Tax & Financial Services offers bookkeeping, tax preparation, tax planning, Profit First consulting, and Virtual CFO services for small businesses in Austin and throughout Texas. We focus on profitability, cash flow, and long-term financial strategy. Disclaimer: Any tax advice provided is not intended or written to be used for the purpose of avoiding penalties under the Internal Revenue Code (Circular 230).
Services
More
Contact Us
737-808-2704
1320 Arrow Point Dr, Ste 501, Office 2, Cedar Park, TX 78613
- Monday - Friday, 8:00 am - 5:00 pm
© Copyright 2026. Profit Pilot Tax and Fianncial Services LLC. All rights reserved.